Yes, you can sell a San Luis Obispo condo as-is to a local cash buyer. Expect an offer within days, no repairs required, and a close that can happen faster than the MLS timeline. You'll still need to meet California disclosure rules and verify escrow and wire instructions before funds move. Start by gathering your ownership and HOA documents, then request a written cash offer.
TL;DR:
- Most San Luis Obispo cash closings occur within a few weeks, but delays can happen due to HOA document response times or title issues.
- Buyers base offers on recent comparable sales minus estimated repairs and holding costs, with smaller discounts for well-maintained condos.
- Sellers must gather key documents early, including HOA disclosures and payoff statements, to avoid escrow delays and title clouds.
- Protect against wire fraud by verifying instructions with a known phone number before transferring funds, as email instructions are a common scam vector.
- An as-is cash sale still requires full disclosure of any known property issues, and legal or tax advice may be needed for complex situations like foreclosures or inheritance.
Table of Contents
- What Does an As-Is Cash Sale Look Like in SLO?
- How Cash Buyers Price an As-Is Condo Fairly
- Step-by-Step: How to Sell Your SLO Condo As-Is
- HOA and Title Issues That Slow Down Condo Closings
- How to Avoid Wire Fraud and Vet a Cash Offer
- Taxes, Foreclosure, and When an As-Is Sale Isn't the Right Fit
- Why I'd Rather Sellers Know the Full Picture Than Just the Fast Answer
- Ready to Request Your Cash Offer?
- Sources
- FAQ
What Does an As-Is Cash Sale Look Like in SLO?
"As-is" doesn't mean you get to skip California's disclosure rules. It means you're not obligated to fix anything before the sale closes, but you still have to tell the buyer what you know about the property's condition. California DRE guidance requires transfer disclosures be delivered as soon as practicable, and skipping that step to speed things up can create legal exposure later, even in a straightforward cash deal.
The mechanics of a cash sale are simpler than a traditional listing, but they still follow a real sequence:
- You get a written offer based on the condo's condition and comparable sales.
- You accept, and the transaction moves into escrow at a title company.
- The title company reviews ownership, payoffs, and any liens against the property.
- Existing loans and liens get paid off at closing, and you receive the remaining proceeds.
Most as-is cash closings in San Luis Obispo typically complete within a few weeks, though delays can occur due to title issues, HOA document responses, or tenant occupancy. A clean title with no HOA disputes tends to close on the faster end.
How Cash Buyers Price an As-Is Condo Fairly
A fair cash offer isn't just "market value minus a discount." Buyers work backward from what the condo could sell for after repairs, then subtract what it will actually cost them to get there.
Several factors shape the number you'll see:
- Recent comparable sales for similar units in your building or complex.
- Estimated repair costs, from cosmetic updates to structural or systems work.
- Carrying costs during the resale window, including HOA dues, insurance, and utilities.
- Any HOA red flags, like pending litigation or a history of delinquent assessments.
- How the buyer plans to resell, whether that's a quick flip or a hold-and-rent strategy.
An offer typically reflects a discount to market value, and that gap covers the buyer's repair budget, holding costs, and a reasonable resale margin. Condos with clean HOA standing and updated systems usually see a smaller discount than units with deferred maintenance or unresolved association issues.
Pro Tip: Organize your mortgage payoff statement, HOA ledger, and any recent repair receipts before you request an offer. Sellers who bring organized documentation to the table tend to see stronger offers and faster closings, simply because the buyer isn't guessing at unknowns.
If you have flexibility on your move-out date, say so upfront. A realistic possession date and a willingness to field more than one bid both give you leverage, even in an as-is sale.
Step-by-Step: How to Sell Your SLO Condo As-Is
Selling a condo without repairs or a listing agent still benefits from a clear sequence. Here's the order that avoids the most common delays:
- Gather your documents. Pull together the deed, current mortgage statements, HOA contact information, recent assessment or account statements, and any lease agreements if the unit is tenant-occupied.
- Request a written cash offer. Ask for specific terms in writing, including contingencies, the proposed closing timeline, and proof of funds if the buyer isn't self-funding.
- Review the offer carefully. Compare the price against local comps and confirm the closing date works for your situation before signing.
- Open escrow with a title company. A reputable local title company will verify payoffs and confirm there are no surprises on title.
- Order HOA documents early. Request these the same week you open escrow. HOAs can take time to respond, and waiting until the last minute is the single biggest cause of delayed condo closings.
- Verify all wire instructions by phone. Call the escrow or title company using a number you look up independently, never one from an email, before sending or receiving any funds.
- Finalize closing details. Confirm your possession date, make sure HOA documents transfer to the buyer, and arrange key delivery.
Each step builds on the last. Skipping the document-gathering stage is the most common reason closings stall past 21 days, since HOAs and title companies often can't move without them.
HOA and Title Issues That Slow Down Condo Closings
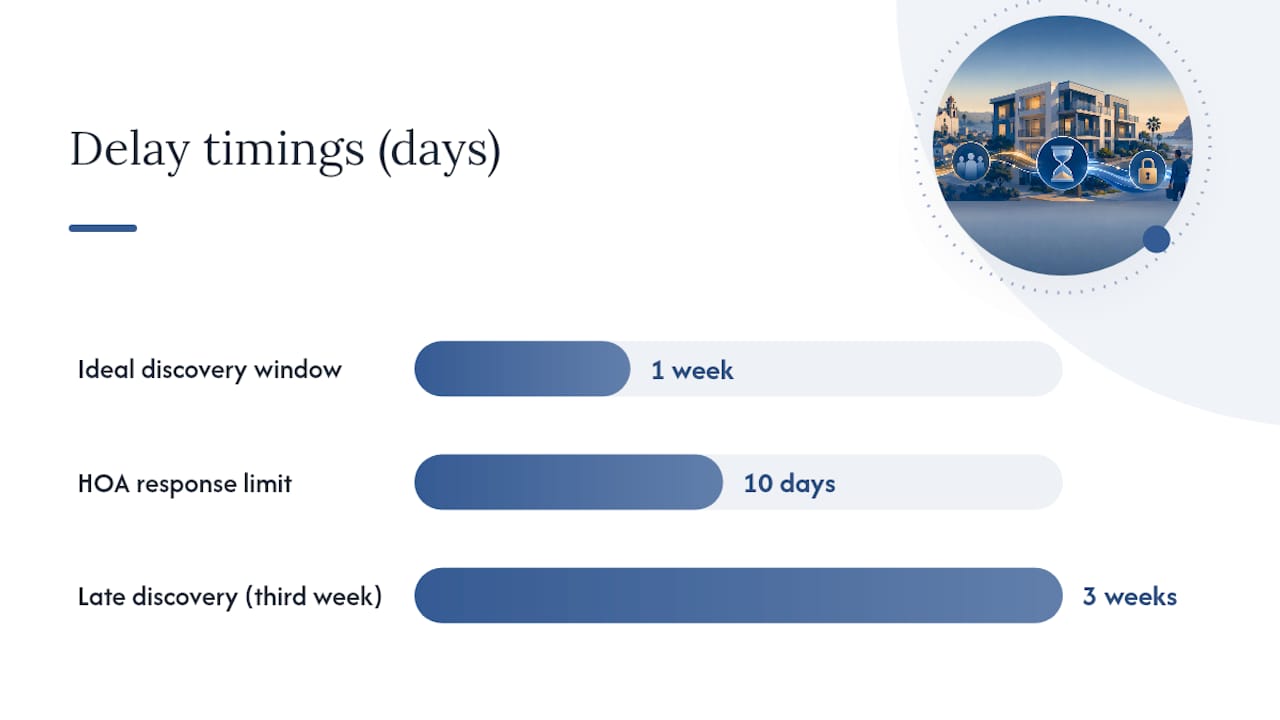
Condo sales carry a layer of paperwork single-family homes don't have, and it trips up sellers who assume an as-is sale means "no paperwork." Under California Civil Code, sellers are entitled to request a specific set of HOA disclosure documents, and associations have up to 10 days to respond once you ask. Fees may apply, but they must be itemized.
Watch for these common blockers:
- Special assessments. A pending assessment on the building can affect the payoff amount and needs to be disclosed before closing.
- Delinquent HOA dues. Unpaid dues attached to the unit typically get settled out of sale proceeds at escrow.
- Title clouds. Judgments, unpaid tax liens, or unresolved ownership disputes need to surface early, since they must be cleared before a title company will insure the transfer.
None of these are usually deal-breakers. They just need to surface in the first week, not the third.
How to Avoid Wire Fraud and Vet a Cash Offer
Real estate wire fraud is one of the fastest-growing scams tied to home sales, and reporting on the issue consistently points to one weak spot: sellers trusting wiring instructions that arrived only by email. A scammer who intercepts an email thread can send convincing-looking instructions that redirect your proceeds to an account you'll never see again.
Protect yourself with a short list of non-negotiable habits:
- Never wire funds based on emailed instructions alone.
- Call your escrow or title company using a phone number you find independently, not one pulled from the same email.
- Confirm the account name and details verbally before any transfer.
- Ask for proof of funds and confirmation that funds have actually cleared, not just been "sent."
- Work with a reputable, licensed title or escrow company, and insist on written closing instructions.
Watch for pressure tactics too. A buyer pushing you to skip escrow, rushing a wire with urgency, or giving inconsistent contact information is a red flag worth stopping for, even if the price looks good.
Taxes, Foreclosure, and When an As-Is Sale Isn't the Right Fit
If you've owned and lived in the condo for at least two of the last five years, you may qualify to exclude up to $250,000 in gain ($500,000 if married filing jointly) under the IRS home-sale exclusion. Some sales still require reporting, so keep your closing statement and consult a tax professional if your situation involves inheritance, divorce, or shared proceeds.
If you're behind on your mortgage, a cash sale isn't always the first move:
- Contact your loan servicer early. HUD counseling guidance recommends reaching out before you fall further behind to discuss short-sale or deed-in-lieu options.
- A short sale can take longer than a cash sale, sometimes up to 120 days, since it requires lender approval.
- If your situation is complex, an inherited property, a rent-to-own arrangement, or a pending divorce, get legal or tax advice before you sign anything.
Why I'd Rather Sellers Know the Full Picture Than Just the Fast Answer
Most articles about selling a condo as-is want to sell you on speed alone. I think that's the wrong pitch. Speed matters, but the sellers I talk to in San Luis Obispo usually care just as much about not getting blindsided by an HOA document delay or a wire transfer that goes sideways.
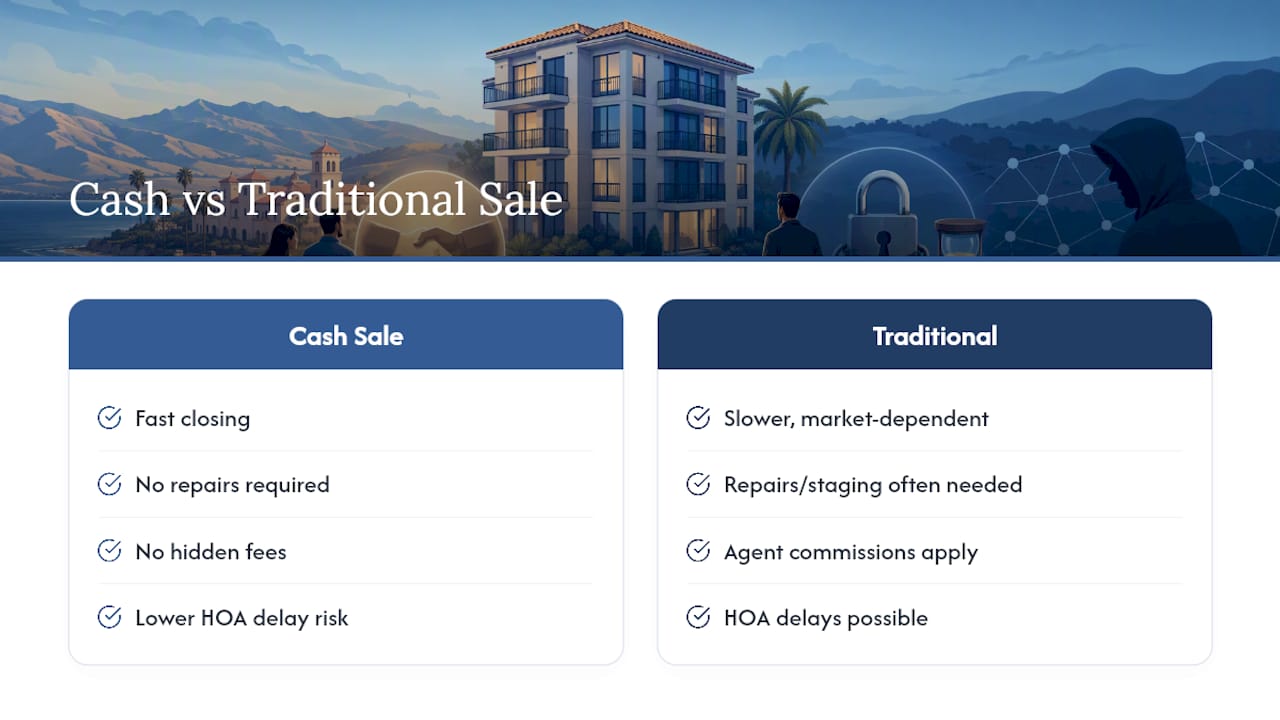
That's really why SLO Cash Buyer - San Luis Obispo County Home buyer exists in the form it does. We buy homes in any condition for cash, which takes repairs, cleaning, and drawn-out negotiations off your plate entirely. We don't ask you to fix anything or pay hidden fees, and we try to be upfront about every number in the offer so you're not left guessing what it's built on.
Where I'd push back on the industry a little: not every seller should take the fastest cash offer available. If you've got time, a clean title, and a condo that shows well, listing traditionally might net you more. But if you're dealing with a tenant situation, deferred maintenance, or a timeline that can't wait, a vetted cash sale with a transparent closing process is often the more respectful path forward, for your finances and your peace of mind.
— Abel
Ready to Request Your Cash Offer?
SLO Cash Buyer - San Luis Obispo County Home buyer is the alternative to listing your condo, hiring an agent, and waiting on repairs. No commissions, no repair punch list, no showings. Just a written cash offer built around your condo's actual condition and your timeline.
When you reach out, have your property address, your HOA's contact information, and a rough mortgage payoff estimate on hand. That's usually enough for us to put together a written offer quickly, and it speeds up the entire process on our end. From there, we'll walk you through escrow and encourage you to independently verify every wire and title detail before funds move, no exceptions.
Ready to see what your condo is worth as-is? Request your cash offer today and find out what a straightforward, no-repair sale actually looks like. If you'd rather explore all your options first, including a traditional listing, check the Cash Offer program details or visit SLO Cash Buyer's main site to compare paths.
Sources
Consult the California DRE's disclosure guidance, HUD's preforeclosure counseling module, IRS Publication 523 on home-sale exclusions, and Schedule D instructions for reporting requirements before finalizing any sale.
- Wire fraud in real estate: consumer reporting and prevention (CNBC)
- HUD housing counselor module — preforeclosure/short sale guidance
- IRS Topic: Excluding the gain from the sale of your home (Publication 523)
- DISCLOSURES IN REAL PROPERTY TRANSACTIONS - RE 6
- California Civil Code (HOA transfer document requirements)
FAQ
How Fast Can I Close on an As-Is Condo Sale in SLO?
Most as-is cash sales close in 7 to 21 days, depending on how quickly HOA documents and title payoffs come together. A clean title and responsive HOA typically land on the faster end of that range.
Do I Still Need to Disclose Problems if I Sell As-Is?
Yes. California law requires you to disclose known material facts about the property even in an as-is sale, per DRE guidance. "As-is" means you won't make repairs, not that you can withhold known issues.
What HOA Documents Will I Need to Provide?
You'll need to request specific HOA disclosure documents under California Civil Code, and the association has up to 10 days to respond. Ordering these early prevents them from becoming the reason your closing slips past three weeks.
Does SLO Cash Buyer Charge Any Fees to Make an Offer?
No. The client provides fair cash offers with no repair requirements and no hidden fees. Current program details are available through the Cash Offer program.
How Do I Make Sure My Closing Funds Aren't Stolen by Wire Fraud?
Never rely on wiring instructions received only by email. Call your escrow or title company using an independently verified phone number to confirm account details before any funds move.