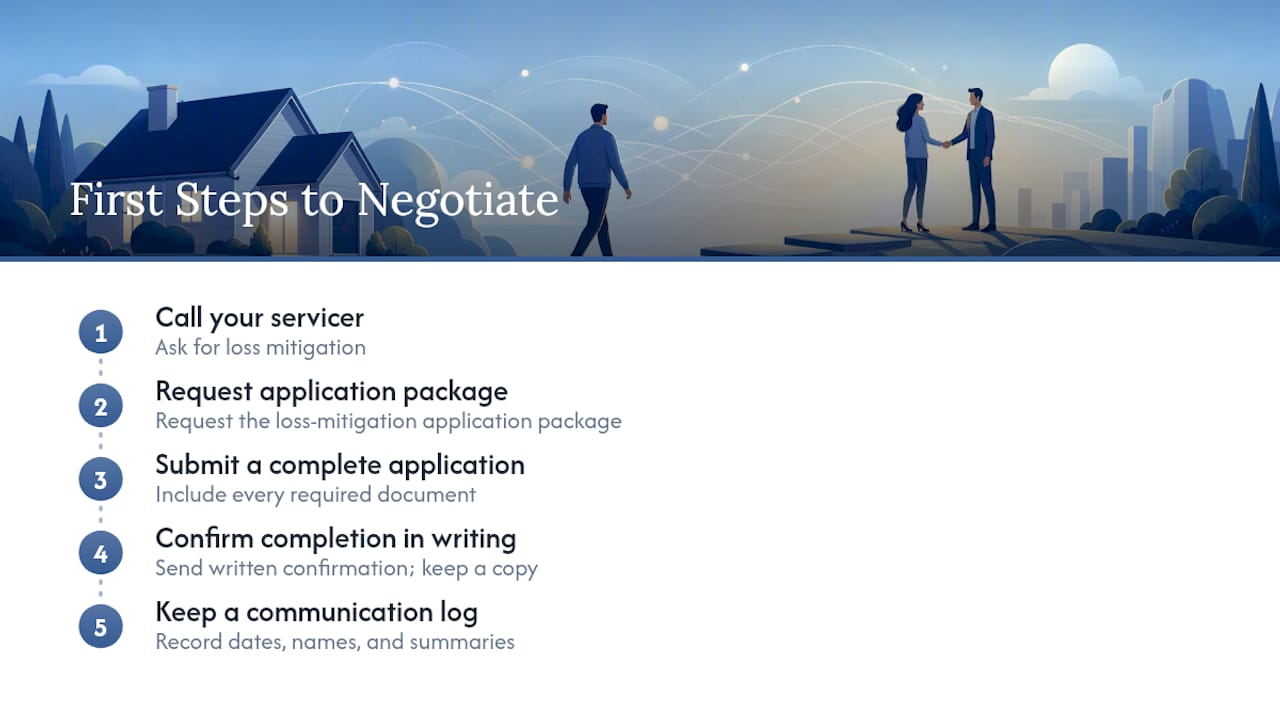
Do this now: contact your mortgage servicer, request loss mitigation, and submit a complete application. Those three steps buy you the time and legal protections you need to avoid or delay foreclosure. This is the negotiate foreclosure with lender steps playbook we walk homeowners through every week. The order matters more than most people realize.
Here's what to do in the next 24 to 72 hours:
- Call your servicer today and ask specifically for "loss mitigation" or "home retention." Do not settle for general customer service.
- Request the loss mitigation package and start assembling documents immediately.
- Start a written log: date, time, representative name, and a one-line summary of every call.
- If you're stuck, call a HUD-approved housing counselor for free help.
- If keeping the home isn't realistic, a fast cash sale can stop a scheduled auction in days, not months.
Key Takeaways
Negotiating foreclosure successfully depends on contacting your servicer immediately, submitting a complete loss mitigation package before the 37-day RESPA deadline, and documenting every interaction in writing.
| Point | Details |
|---|---|
| Call servicer first | Ask specifically for loss mitigation or home retention, not general customer service. |
| Submit before 37 days | A complete application filed more than 37 days before a sale date triggers federal dual-tracking protection. |
| Keep a communication log | Record date, time, representative name, and summary for every call or email. |
| Get free help if stuck | HUD-approved counselors and the NFCC negotiate with servicers at no cost. |
| Consider a cash sale as backup | SLO Cash Buyer - San Luis Obispo County Home buyer can close a purchase fast when retention options run out of time. |
Table of Contents
- Negotiate Foreclosure With Lender Steps: Your First 30 Days
- What Documents Go Into a Complete Loss Mitigation Package
- What Should You Say When You Call Your Lender?
- Which Loss Mitigation Option Fits Your Situation
- When Your Lender Won't Cooperate
- Will Your Lender Actually Approve Your Request?
- How Long Does Foreclosure Negotiation Actually Take?
- Does a Loan Modification Hurt Your Credit Score?
- Frequently Asked Questions
- Sources
Negotiate Foreclosure With Lender Steps: Your First 30 Days
The clock starts the moment you miss a payment, not when the servicer sends its first scary letter. Contacting your servicer immediately expands your available workout options, and every week you wait shrinks that list. Here's the order that actually works.
- Find your servicer's loss mitigation line. It's usually a different number than the general customer service line printed on your statement. Check your monthly bill or the servicer's website for a "hardship" or "assistance" department.
- Call and ask directly: "I need to apply for loss mitigation. Can you route this to your home retention department?" Ask outright whether a sale date has been scheduled. You need this answer before anything else.
- Request the loss mitigation application within that same call. Ask how they prefer it delivered: online portal, fax, email, or mail.
- Submit your complete package and get written confirmation it's marked "complete." This single word matters legally.
- Track the 37-day window. Under federal dual-tracking protections, a complete application submitted more than 37 days before a scheduled sale forces the servicer to pause foreclosure while they review it. Submit late, and that protection disappears.
- Watch the California-specific milestones. In a nonjudicial foreclosure, the state's process runs from Notice of Default through a 90-day window to Notice of Sale and then the trustee's sale. Every day inside that window is a day you can still negotiate.
Pro Tip: Ask your servicer, in writing, for the exact date your application was received and the date it was marked complete. Servicers sometimes claim a file was incomplete weeks after the fact, and having that date in an email or letter is your best defense.
Once you've submitted, follow up weekly. Confirm every phone call with a short email that says, in plain language, what was discussed and agreed. If a representative promises something over the phone, ask them to send it in writing before you hang up. Servicers handle thousands of files, and paper trails move faster than memory.
What Documents Go Into a Complete Loss Mitigation Package
A "complete" application isn't a vague standard. Servicers require a specific set of documents, and missing even one can send your file back to the bottom of the pile.
- Signed servicer application form (often called a Request for Mortgage Assistance)
- A hardship letter explaining what happened and when
- Recent pay stubs, usually the last 30 to 60 days
- Two years of tax returns or a signed IRS transcript request
- Two to three months of bank statements, all accounts
- Proof of any unemployment, disability, or other benefit income
- A monthly household budget worksheet
Organize everything behind a cover sheet listing what's included, in the order the servicer's checklist requests it. Keep your originals and send copies only.
Pro Tip: Send your package by a traceable method, certified mail with return receipt or a portal upload with a confirmation screenshot, and save that receipt. A written communication log paired with delivery proof is often the deciding factor when a servicer claims it never received something.
What Should You Say When You Call Your Lender?
The words you use on that first call steer where your file lands. Use these instead of generic small talk:
- "I'm calling to apply for loss mitigation. Please route my file to the home retention department, not collections."
- "Is there a sale date scheduled on my loan right now?"
- "I want to confirm in writing once my application is marked complete."
- "Who is my single point of contact, and what's their direct line?"
For your hardship letter, keep it short: state the cause (job loss, medical bill, divorce), your current income, and a specific proposed payment you can sustain. Close by requesting a trial payment plan or a full modification review. Ask for written confirmation of any agreement before you make a payment based on it.
Which Loss Mitigation Option Fits Your Situation
Not every homeowner needs the same fix, and asking for the wrong one wastes time you don't have.
- Forbearance pauses or reduces payments temporarily. It fits a short-term hardship like a medical event or brief job loss where income is coming back.
- Repayment plan spreads missed payments across future months. It works if your income has recovered and you can afford your normal payment plus a bit extra.
- Loan modification permanently changes your rate, term, or balance. This is the right ask when your hardship is long-term and your old payment simply isn't affordable anymore.
- Pre-foreclosure sale or deed-in-lieu ends the loan without a trustee's sale on your record. These fit when keeping the home isn't realistic, though relocation and a possible deficiency balance are real trade-offs to weigh first.
When Your Lender Won't Cooperate
If your servicer stalls, loses paperwork, or ignores deadlines, escalate immediately rather than waiting for a callback.
- Contact a HUD-approved housing counselor or the NFCC for free negotiation help and application review.
- Cite dual-tracking protections under RESPA / 12 CFR 1024.41 if a sale proceeds despite a pending complete application.
- File a formal appeal if denied; servicers must offer one for most modification decisions.
- Ask an attorney whether Chapter 13 bankruptcy could pause a scheduled trustee's sale and buy time to negotiate.
- If none of that works fast enough, a quick cash sale can stop an auction before it happens.
Will Your Lender Actually Approve Your Request?
Approval odds vary a lot by option, and being honest with yourself about which one fits saves weeks of wasted back and forth. Forbearance is the easiest approval because it's temporary. Servicers grant it readily when your hardship has a clear end date and your account was current or only recently delinquent.
Loan modification approval depends largely on whether your proposed new payment aligns with your documented income after the hardship. Servicers run this through an affordability test, and if your income still can't support even a modified payment, they'll steer you toward a repayment plan instead, or toward a sale option. Submitting a complete, organized packet with a clearly proposed solution improves your odds because underwriters evaluate paperwork, not phone promises.
A Trial Payment Plan often precedes a permanent modification. Missing a payment during the trial, even by a few days, can restart the whole process or trigger a denial, so treat those months as non-negotiable. Repayment plans get approved fastest when the missed amount is small relative to your income; ask your servicer directly what repayment terms they consider "affordable" for your loan type before you counter with your own number.
If your file has already been denied once, ask what specific income-to-payment ratio pushed it over the edge. That number tells you whether to reapply with stronger documentation or shift toward a disposition option.
How Long Does Foreclosure Negotiation Actually Take?
Set your expectations by the calendar, not by hope. From your first call to a servicer decision on forbearance, expect a few days to a couple of weeks if your paperwork is clean. Loan modification review usually takes several weeks once your file is considered complete, sometimes longer if additional documents are needed.
The legal backbone in California runs on a fixed schedule: Notice of Default, then a 90-day waiting period, then Notice of Sale, then the trustee's sale itself. Submitting your complete loss mitigation application more than 37 days before any scheduled sale date is what triggers your federal pause protection, so count backward from that sale date the moment you learn of it. A Trial Payment Plan, if offered, generally runs for a few months; missing payments during that period can reset your timeline.
Realistically, budget 60 to 90 days from first contact to a final decision on most modification requests, and start the process the day you know you'll miss a payment, not after the second or third notice arrives.
Does a Loan Modification Hurt Your Credit Score?
Yes, but less than a completed foreclosure. Missed payments leading up to any negotiated solution already show up on your credit report, and that damage happens regardless of which option you land on. A forbearance or repayment plan reported correctly tends to cause less lasting harm than a modification, which some servicers report as "settled" rather than "paid as agreed."
A full foreclosure can significantly reduce your credit score and stays on your report for several years. A loan modification or short sale generally causes a smaller, shorter dip. Once your new terms are in place, rebuilding is straightforward: pay every payment on time going forward, keep credit card balances low, and pull your credit report to confirm the servicer is reporting your account status accurately. Errors here are common, and disputing them early prevents years of unnecessary damage.
Lessons From Handling Foreclosure Prevention Cases
The homeowners who keep their homes almost always start early, log every call, and get HUD-approved counseling before paying anyone for help. A complete file with consistent follow-up beats a perfect hardship letter with gaps in the paperwork. And sometimes the smartest move isn't retention at all. It's recognizing early that a fast cash sale stops the auction clock when nothing else will.
If Keeping the Home Isn't Possible, a Fast Cash Sale Can Still Stop the Auction
Sometimes the numbers just don't work, no matter how strong your hardship letter is or how fast you assembled your documents. SLO Cash Buyer - San Luis Obispo County Home buyer buys homes in any condition for cash, with no repairs, no cleaning, and no hidden fees, which matters when a trustee's sale date is closing in and you have no time left to fix up a property for a traditional listing.
If your trial payment plan failed, your modification was denied, or relocation has simply become the more realistic path forward, a cash sale can close in days instead of the weeks a retail sale demands. Reaching out costs nothing and locks you into nothing. Request a no-obligation cash offer today, and if you want to understand what closing actually looks like once you accept, this quick sale timeline walks through each stage so you know exactly what to expect before your sale date arrives.
Frequently Asked Questions
What are the first steps to negotiate foreclosure with lender officials? Call your servicer and ask for loss mitigation, request the application package, submit it complete, and confirm that completion in writing. Those four moves protect your legal options and open the door to every other remedy.
How long does a lender have to respond to a loss mitigation application? Timelines vary by servicer, but a complete application filed more than 37 days before a scheduled sale forces a pause on foreclosure activity while it's under review, per federal dual-tracking rules.
Can I negotiate foreclosure without hiring an attorney? Yes. HUD-approved housing counselors handle most negotiations for free, and many homeowners successfully self-negotiate using a complete application and a clear communication log.
What happens if my lender schedules an auction while I'm still negotiating? If your complete application was submitted more than 37 days beforehand, the sale should be paused under dual-tracking protections. If it proceeds anyway, escalate to a housing counselor or attorney immediately, or consider a fast cash sale to close before the auction date.
Will a loan modification stop foreclosure permanently? A completed and honored modification ends the foreclosure process for that loan. Missing payments on the new terms, however, can restart foreclosure proceedings, so treat the new payment as non-negotiable going forward.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Usa
- Avoiding foreclosure | HUD
- HUD servicing and loss mitigation updates (2026)
- Your rights in a nonjudicial foreclosure | California Courts